Category: Uncategorized
Key Takeaways
- Aiken County Public School District serves 23,000+ students across 35 schools with 21 elementary, 12 middle, and 8 high schools, though academic performance shows 48-51% reading and 34% math proficiency.
- The county also offers 15 private schools with top options including Mead Hall Episcopal ($11,000+ tuition, 100% college placement).
- Private school enrollment represents 10% of the K-12 population, above the state average.
Whether moving to a new Aiken County neighborhood or settling in the area for the first time, homebuyers often compare the various public and private schools available to their children.
Public Schools in Aiken
The Aiken County Public School District provides public education for students across the county. The district has over 23,000 students spread across 21 elementary schools, 12 middle schools and eight high schools. Around 48%- 51% of students in the district are proficient in reading, while roughly 34% achieve math proficiency.
Top High Schools in Aiken
Top Aiken high schools offering grades nine through 12 include:
- Aiken Scholars Academy
- North Augusta High School
- South Aiken High School
Top Middle Schools in Aiken
Top Aiken middle schools offering grades six through eight include:
- New Ellenton Middle
- North Augusta Middle
- Paul Knox Middle
Top Elementary Schools in Aiken
Top Aiken elementary schools offering pre-k through grade five include:
- Clearwater Elementary
- Belvedere Elementary
- Chukker Creek Elementary
Private Schools in Aiken
Families in Aiken County can choose between 15 private schools. Each private school has a religious affiliation.
Over 2,500 students attend private schools in Aiken County. While South Carolina’s private schools comprise 8% of the student population, 10% of K-12 students in Aiken County attend a private school.
Mead Hall Episcopal School
Mead Hall Episcopal School is Aiken County’s premier private school. With a tuition over $11,000 for the highest grade, over 370 students attend the school. All of its students graduate and pursue post-secondary education.
South Aiken Baptist Christian School
South Aiken Baptist Christian School is another top choice for private K-12 education in Aiken County. Around 230 students attend the school, which costs over $6,000 annually. All South Aiken Baptist Christian School students graduate and receive college placement.
Victory Christian School
Victory Christian School is a private school in the North Augusta portion of Aiken County. This school is small, hosting 90-150 students each year. Tuition ranges from $6,250-$6,750, depending on the grade level. Around 75% of Victory Christian School graduates advance to colleges and universities.
Finance Your Move to Aiken County, South Carolina
Assurance Financial can provide the financing and tools you need to move to Aiken County. You can use our mortgage calculator to estimate your payment while evaluating the cost of private school versus public education in Aiken County. To apply for a mortgage, complete our 15-minute pre-qualification process online or find your local loan officer to discuss options.
Assurance Financial Awarded at Total Expert’s 2024 Accelerate Conference
July 5, 2024
We’re proud to announce that Assurance Financial has been recognized in two categories at Total Expert’s 2024 Accelerate conference.
The fourth annual Expy Awards celebrate Total Expert customers for their ability to surpass the limits of what is possible to provide unparalleled customer experiences and drive the financial services industry forward. Winners are chosen for their utilization of the platform to the highest extent to drive business growth and build authentic customer connections. This year’s winners were announced at Total Expert’s 2024 Accelerate Conference in Minneapolis, Minnesota, where financial services leaders gathered to share winning strategies.
- The Adopter: Without universal adoption, even the most innovative technology becomes shelfware. For Assurance Financial, the universal buy-in of the Total Expert platform into daily operations was a route to business growth and overall company success. They noted substantial increases in new loans, funded loans, email click-through rates, and task completion rates correlating to a growth in customer retention
- Firestarter – Director of Marketing Lindsi Flynn: A user who embodies innovation, growth, and industry disruption within their organizations. Firestarters are at the forefront of driving positive change, sparking innovation, and propelling their companies toward a dynamic future.
“Our Expy Award-winners are some of the most forward-thinking organizations in the industry, empowering their workforce with the resources to meet growing customer expectations,” said Joe Welu, founder and CEO of Total Expert. “They are one step ahead of the industry—changing the way their teams leverage data by clearly recognizing customer needs, improving the decision-making process, and establishing more personalized customer journeys. We’re proud to celebrate their success and inspiring dedication to customer-centric innovation through Total Expert.” Learn more here.
Bursting with personality and unforgettable experiences, Atlanta is the crown jewel of the South. This vibrant city is home to many beautiful residential neighborhoods that offer a vibe just as eclectic as the city. Whether you’re looking for a modern home, a piece of Southern heritage or a bit of both, there are many available homes just waiting for you to make an offer.
Before you make an offer, however, you may want to take some time to learn about the latest Atlanta housing market trends so you can navigate the buying process with ease.
Housing Trends
With a competitive housing market, most homes in the Atlanta area receive multiple offers and sell around two months after listing. Current housing market trends in Atlanta show that single-family homes have seen increases in sale price, number of homes sold and days on the market. Conversely, townhouse and condo sales have seen a decline in sale prices.
Current Housing Demand
There is a high demand for houses in Atlanta, with the average home selling at slightly below the listing price. More popular homes generally sell for the asking price and are only on the market for a few weeks. Most single-family homes, townhouses and condos sell for their asking price.
Homeowner Migration
As a major city, Atlanta sees a high rate of people moving in and out of the city. While most people choose to remain in the Atlanta metropolitan area, many homeowners are moving to cities like Washington, D.C., and Macon, Georgia.
Many people are also looking to move to Atlanta from cities across the country. Some of the top locations people are moving to Atlanta from include New York City and Los Angeles, California.
Schools in Atlanta
Since Atlanta is the largest city in Georgia, it’s home to multiple school districts. Since Atlanta offers school choice, your child can attend school in another district if space allows. Some of the many options for school districts include:
- North Atlanta Cluster
- Douglas Cluster
- Mays Cluster
- Therrell Cluster
- Grady Cluster
- Washington Cluster
- Carver Cluster
- Jackson Cluster
- South Atlanta Cluster
Atlanta’s Climate
Like any city, Atlanta faces environmental risks like flooding, fire, wind and heat. Atlanta is at a moderate risk for flooding and fires and a significant risk for wind and heat. Atlanta’s major environmental risk is hurricanes. In the next few decades, Atlanta will also experience more days with temperatures higher than 100 degrees Fahrenheit.
Find Personalized Mortgage Options With Assurance Financial
At Assurance Financial, we want to make financing your dream home easy. From friendly loan advisors to a simple application, we make it easy to find a financing option that works for you. Contact us to learn more about our services, or complete a mortgage application today!
Taking out your first mortgage is a huge life step. A mortgage is a critical tool to have — it allows you to become a homeowner without putting down hundreds of thousands of dollars on the spot, and it lets you pay off your loan over time. About 96% of first-time homebuyers finance the purchase with a mortgage.
But mortgages are immensely complex, and many homeowners have questions when they first get started. How do mortgage payments work, exactly? And what is included in your monthly mortgage payment? We’re here to answer your questions so you can approach your new mortgage with confidence.
Topics Covered
- What Are Mortgage Payments?
- How Does a Mortgage Loan Work?
- What Is Included in a Mortgage Payment?
- Mortgage Payment Formula
- Mortgage Vs Loan
- Frequently Asked Questions About Mortgage Payments
What Are Mortgage Payments?
What is a mortgage payment? Mortgage payments are the payments you make on a long-term loan that enables you to buy your home.
Almost everyone who owns a home has a mortgage and makes mortgage payments. Homeowners typically make these payments monthly, over a fixed period of years. Some standard options include 15-year and 30-year mortgages.
What are the advantages of spreading out mortgage payments across more or fewer years? Each approach comes with pros and cons:
- Shorter mortgages: Shorter mortgages tend to have lower interest rates and allow the homeowner to pay less interest overall. The tradeoff is that because the schedule becomes more compressed, these mortgages require higher monthly payments.
- Longer mortgages:Longer mortgages tend to have higher interest rates. So homeowners who choose these mortgages will pay more interest overall. The appealing tradeoff is that by spreading the payments over a longer term, homeowners can lower their monthly payments to more affordable sums. So extended options are often attractive to homeowners looking to create more room in their budgets each month.
Benefits of Making Regular Mortgage Payments
Paying down your mortgage provides you with a couple of different benefits. One is that it reduces the amount of debt you have. As you slowly, steadily make payments, you decrease your debt burden. You increase your debt-to-income ratio, making yourself a more attractive borrower if you decide to take out new loans. You also get a little closer to having your home paid off and having a bit more cash to spend each month.
The second benefit is that you accrue home equity. Home equity is the amount of your home that you have paid off. It equals the value of your home minus the value of your remaining mortgage. So the more of your mortgage you pay down, the more home equity you’ll have. Maintaining as much home equity as you can is an excellent strategy for maintaining financial stability. You can also borrow strategically against your equity by taking out home equity loans — to perform renovations, say, and boost the eventual resale value of your home.
How Does a Mortgage Loan Work?
A mortgage loan is a type of loan that is used to purchase a property, such as a home or a piece of land. You borrow money from a lender to purchase the property and the property serves as collateral for the loan. Here’s how it works:
- Application: You apply for a mortgage loan with a lender, which involves providing personal and financial information.
- Pre-approval: The lender evaluates your creditworthiness and pre-approves you for a certain loan amount.
- Property search: You search for a property to purchase within the pre-approved loan amount.
- Property appraisal: The lender hires an appraiser to determine the value of the property to ensure it is worth the amount being borrowed.
- Loan approval: The lender approves the loan, and you sign a mortgage agreement that outlines the terms and conditions of the loan.
- Down payment: You make a down payment on the property, which is a percentage of the purchase price.
- Closing: You meet with the lender to finalize the transaction. This involves signing a promissory note and a deed of trust, which gives the lender a security interest in the property.
- Repayment: You make monthly payments on the loan, which typically include principal, interest, taxes and insurance. The loan is usually repaid over a period of years.
- Ownership: Once the loan is fully repaid, you own the property outright.
What Is Included in a Mortgage Payment?
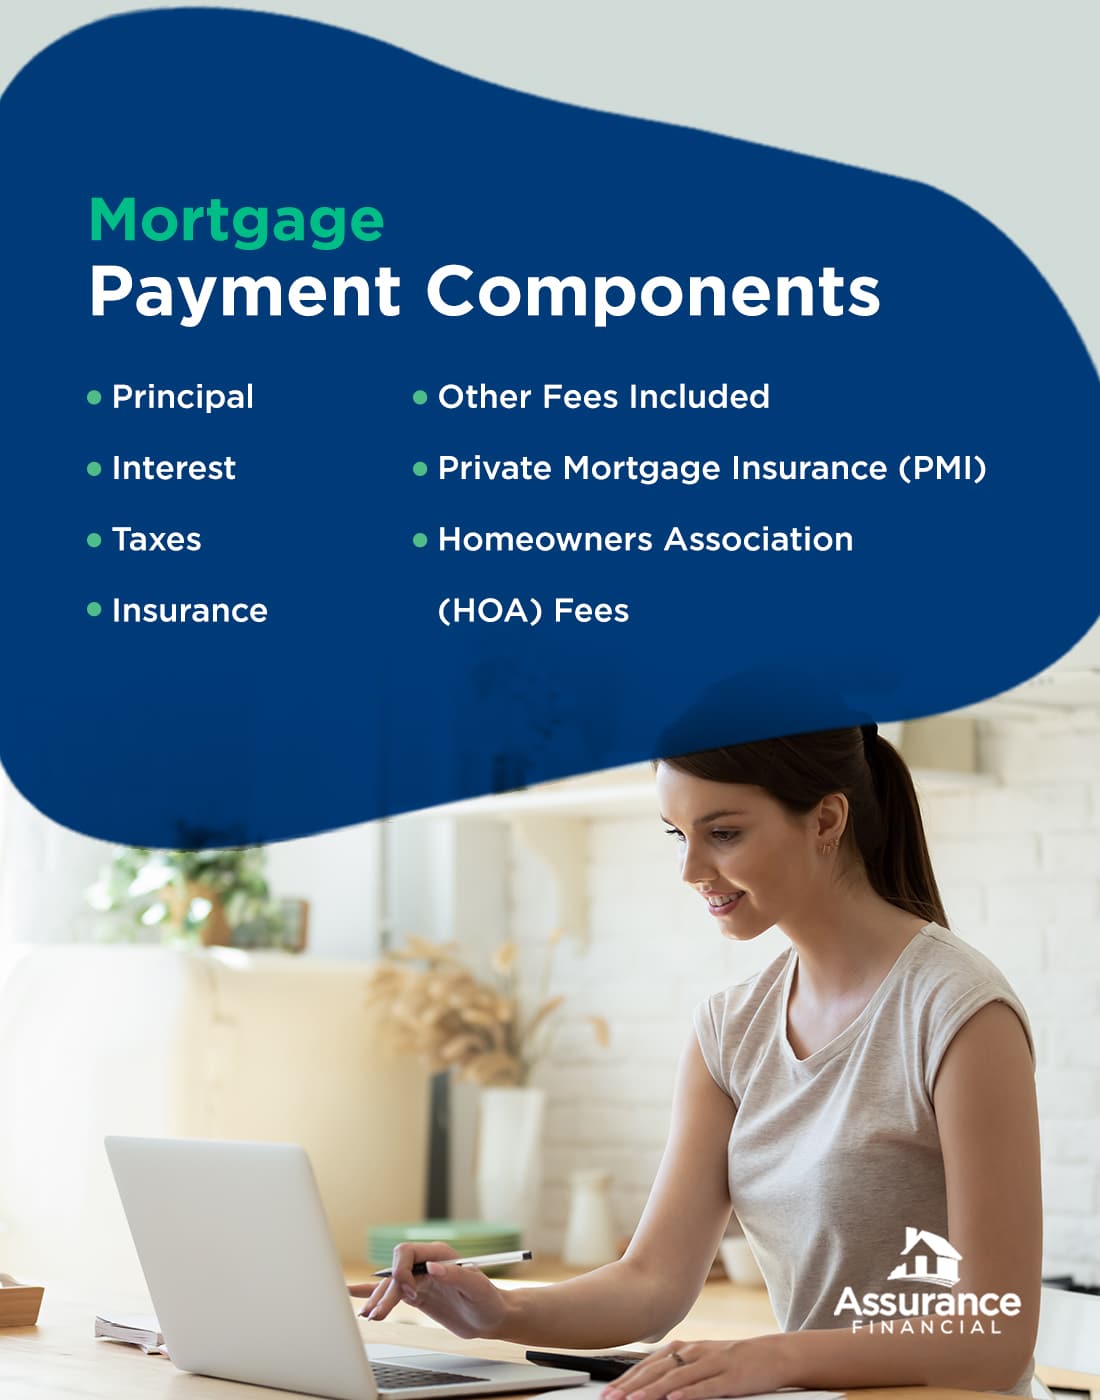
Your mortgage payments consist of many different components that all combine into a single sum. Four main components — principal, interest, taxes and insurance (PITI) — go into the makeup of your mortgage payments, and additional fees may be included as well.
Below is a breakdown of those components:
1. Principal
The principal is the amount of money you borrowed from your mortgage lender and have to pay back. Generally, that sum is the price of your home minus your down payment. Say you bought a $300,000 house and put down a 20% down payment of $60,000. Your principal is then $300,000 – $60,000, or $240,000.
Most of your mortgage payment each month goes toward paying down the principal and interest. The part of your monthly payment that goes toward your mortgage principal is what pays down your loan and builds your home equity. Most mortgage structures favor paying down more of the interest at the beginning of the loan and more of the principal at the end.
2. Interest
Interest is the amount charged on the principal because the lender is loaning you the money. The purpose of interest is to reward the lender for taking the risk of lending to you. Charging interest is how lenders make money, keep their businesses running and pay their employees.
Interest rates vary from mortgage to mortgage, and conditions can change quickly. Interest rates decreased between 2018 and 2021, with average interest rates on a 30-year fixed-rate mortgage falling to as low as 2.65% in January 2021. Interest rates in 2023 are somewhat elevated, but many experts predict decreases as the year goes on.
The amount of interest included in your monthly mortgage payment varies inversely with the amount of principal included. At the beginning of your home loan, your payments will include a higher proportion of interest. Toward the end of your loan, that proportion will be much lower.
3. Taxes
Some mortgage payments also include real estate taxes, also known as property taxes.
Local governments assess property taxes to fund public services like schools, fire and police departments and the public works departments that maintain municipal infrastructure. The government requires these taxes annually, but homeowners typically pay them in monthly installments as part of their mortgage payments.
How does the local government receive those funds if it collects them only once per year? Your lender will hold the taxes for you in escrow and pay them once they come due.
If you’re looking at your property taxes and wondering why they don’t line up with the price of your home and your tax rate, remember that counties usually base property taxes on the assessed value of your home rather than on the purchase price. A property assessor looks over your house and then tells the local government its value.
So if you got a massive house at a great price, you might still have hefty property taxes incorporated into your mortgage payments. Say you bought a $600,000 home for $500,000. If the county property tax rate is 1.5%, you’ll pay $9,000 in property taxes for the year — $600,000 x 0.015. Divided by 12 months, that’s $750 in taxes on your mortgage payment.
4. Insurance
Does a mortgage payment include insurance? Usually, though not always. Your mortgage payment generally includes your property insurance payment and your private mortgage insurance (PMI) payment if applicable.
Property insurance is the insurance that covers your home in the event of a disaster like a fire, hurricane, tornado or even a burglary. It can include homeowners insurance as well as additional riders like flood and earthquake insurance.
Property insurance takes most of the risk from the homeowner and transfers it to the insurance company. So you’ll pay a little more each month, but you’ll pay a lot less in repair and replacement costs if disaster strikes.
Insurance payments work similarly to property tax payments. You’ll include them as part of your monthly mortgage payment even though they’re due only once a year. Your lender will hold the insurance money in escrow for you and pay it when the insurance company requires it.
5. Other Fees Included
Your mortgage payments may also include miscellaneous other fees, such as loan processing fees. These fees are likely to account for a minimal percentage of your overall monthly payment.
6. Private Mortgage Insurance (PMI)
If you make a down payment of less than 20% when you buy your home, your lender will likely require you to take out private mortgage insurance (PMI). Lenders use your down payment amount as a proxy to assess the risks associated with lending to you. Your PMI costs add a little to your mortgage payment each month.
Unlike property insurance, which protects you in case of a disaster, PMI protects your lender. It covers your lender if you become unable to make your monthly mortgage payments. If you miss payments, your PMI will kick in to cover the costs so your lending company doesn’t lose its investment. PMI will not protect you, however. If you fall behind on payments, you can still lose your home to foreclosure even though you have PMI coverage.
PMI is also important to many lenders because it enables them to sell loans to other investors. Having insurance backing minimizes these investors’ risk and makes them more willing to take on the loans.
PMI is relatively easy to remove from your mortgage payments after a while. Generally, once you’ve accumulated 20% home equity, you’ve convinced your lender of your fiscal reliability and can request to drop your PMI. Alternatively, you can sometimes stop your PMI at the midpoint of your amortization schedule — after the 20th year of a 40-year mortgage, for instance.
Additionally, once you pay off more of your loan, your mortgage insurance should drop automatically — usually once the balance reaches 78% or less of the original mortgage amount.
7. Homeowners Association (HOA) Fees
If you belong to an HOA, your mortgage payment sometimes includes HOA fees. These fees keep you in good standing with your HOA and, as with the lumped-in insurance and tax payments, offer convenience by minimizing the number of separate payments you must make.
Check out our mortgage calculators to help you better prepare for your loan.
Mortgage Payment Formula
The formula to calculate the monthly mortgage payment is:
M = P [ i(1 + i)^n ] / [ (1 + i)^n – 1 ]
Where:
M = Monthly mortgage payment
P = Principal amount borrowed (the loan amount)
i = Monthly interest rate
n = Number of monthly payments (loan term in years multiplied by 12)
For example, let’s say you take out a $200,000 mortgage loan with a 4% annual interest rate and a 30-year loan term. To calculate the monthly mortgage payment:
P = $200,000
i = 4% / 12 = 0.003333 (monthly interest rate)
n = 30 x 12 = 360 (number of monthly payments)
M = $200,000 [0.003333(1 + 0.003333)^360] / [(1 + 0.003333)^360 – 1]
M = $954.83 (rounded to the nearest cent)
Therefore, your monthly mortgage payment would be $954.83. Note that this formula does not include taxes, insurance or any other additional fees that may be included in the monthly mortgage payment.
Mortgage vs. Loan
A mortgage is a type of loan that is specifically used to purchase a property, such as a home or a piece of land. The property serves as collateral for the loan, which means that if you don’t make the mortgage payments, the lender can foreclose on the property and sell it to recoup their losses.
On the other hand, a loan is a more general term that can refer to any type of borrowing, such as a personal loan, a car loan or a business loan.
The main differences between a mortgage and a loan are:
- Purpose: A mortgage is used to purchase a property, while a loan can be used for a variety of purposes.
- Collateral: A mortgage is secured by the property being purchased, while a loan may or may not require collateral.
- Repayment period: Mortgages typically have longer repayment periods than other types of loans, often spanning decades.
- Interest rates: Mortgage interest rates are typically lower than interest rates for other types of loans due to the fact that they are secured by the property being purchased.
Frequently Asked Questions About Mortgage Payments
Below are a few commonly asked questions about mortgage payments and how they work:
1. When Are Mortgage Payments Due?
Mortgage payments are typically due on the first of every month, but they work differently from rent payments in terms of what month they cover. With rent payments, you typically pay upfront, putting down money on the first of the month for the upcoming month. With mortgage payments, on the other hand, you generally pay in arrears — paying for the previous month instead of the upcoming one.
2. When Do Mortgage Payments Start?
When new homeowners close on a house, paying the closing fees as they do, they often wonder how soon their mortgage payments will kick in, hoping for a little breathing room.
And they typically get it. Because you pay in arrears, your first mortgage payment is usually due on the first day of the month after the month you closed. Say for example that you closed on your house on January 19. Your first mortgage payment would be due on March 1 and would cover February.
What about the interest due for January? That interest generally rolls into your closing costs. You’ll be able to see the exact amount in your closing disclosure forms, along with your interest rate, loan amount and monthly payments.
3. Do Mortgage Payments Go Down Over Time?
If you have a fixed-rate mortgage, your mortgage payments will not drop over time.
However, the amounts that comprise your loan do change over time due to your amortization schedule — the schedule of your payments. This schedule impacts how interest payments and principal payments are distributed. Generally, your initial mortgage payments favor your interest. You’ll be paying off more of your interest at first and less of the principal. Over time, as you pay down your home loan, your payments start to include more principal and less interest.
The result is that you pay down your interest faster than you pay down your principal. Why?
At the beginning of your loan, you naturally have a higher loan balance. So you owe more interest every month once you apply your interest rate to that loan balance. As time goes by and your loan balance decreases, you’ll owe less interest every month. So most of your payment will then go toward the principal, even though your total payment stays the same.
All that said, your mortgage payments may change slightly because of alterations in your insurance or tax rates. If your home’s value rises, for instance, your property taxes will likely rise as well, increasing your overall mortgage payment.
4. What Happens if I Make a Large Principal Payment on My Mortgage?
If you make a large payment on your mortgage, the extra payment goes toward paying down your principal. So in many cases, making a large payment is advantageous if you can afford it. It enables you to pay down your mortgage sooner and build equity faster.
And paying down the principal also helps you reduce your interest. The reason is that your lender calculates your interest from the amount of your principal. So if you lower your principal, you’ll lower your remaining interest as well.
With some mortgages, though, your lender will assess a prepayment penalty if you pay your mortgage down early. The prepayment penalty exists to compensate the lender for the interest it loses if you pay off your mortgage more quickly than expected. So you’ll probably want to sit down and do the calculations to figure out the best option for your finances. Determine whether your finances will benefit more if you pay your mortgage early and lower its overall cost or if you pay it slowly and steadily to avoid the prepayment penalties.
5. What Happens if I Miss a Mortgage Payment?
If you miss a mortgage payment, the penalties you’ll face depend on how late you were and how often you’ve missed payments in the past.
First Payment
Generally, the first time you miss a payment, you’ll receive a short grace period in which to get your payment up to date. That grace period is often about 15 days. Mortgage lenders need to receive their money — still, they understand that life happens, and they don’t want to penalize otherwise good, reliable clients. If you make your payment within that grace period, you probably won’t incur any penalties.
Second Payment
If you miss a second payment, or if the grace period goes by and you still haven’t made your first missed payment, you’ll start to feel the consequences. The first thing your lender will do if you miss mortgage payments or don’t pay within the allotted grace period is to impose a late fee. You’ll still be responsible for the missed payment, and you’ll have to pay a little extra as well. The late fee acts as a deterrent to discourage you from missing future payments. Depending on its policies, your lender may also report your delinquency to the credit bureaus. If your lender reports the late payment, you’ll take a hit to your credit score.
Once you miss two payments, your lender considers you to be in default on your mortgage. At this point, the lender is likely to become stricter and more forceful in its communications with you about making payments. However, most lenders don’t want to foreclose on a home unless they have no other options, so you can very likely still work out a payment deal at this point.
Third Payment
After three missed payments, you will receive a letter from your lender advising you that you have 30 days to make the missed payments, and then your lender will begin foreclosure proceedings. If you don’t make payments during that 30 days, foreclosure will start.
The upshot is that you’ll need to ensure you make your mortgage payments on time each month so you can stay in the home you love. Remember that your mortgage is a secured loan — your house and property make up the collateral to secure it. If you fail to make mortgage payments, you could lose your home to foreclosure.
6. Can I Change My Mortgage Payment Amounts?
If you have a fixed-rate mortgage, you’d usually need to refinance your home to change your mortgage payment amounts.
Many homeowners refinance their homes at some point to lower their interest rates, increase or reduce the mortgage length, or reduce their monthly bills. Refinancing is a considerable undertaking since you’re applying for a mortgage all over again. Still, it is well worth the trouble in many scenarios.
To obtain changeable mortgage payments, you can also take out an adjustable-rate mortgage. If you have an adjustable-rate mortgage, your monthly payments will change often as your interest rates fluctuate.
With an adjustable-rate mortgage, the interest rate remains fixed for a determined time and then adjusts at predictable intervals — every five years, every year, even every month. At the end of the predetermined period, the interest rate adjusts to reflect the current market rate.
Adjustable-rate mortgages can be a risky gamble — you can’t be certain how your rates will change. If you feel confident that interest rates will drop over time, though, you might consider taking out an adjustable-rate mortgage to reap the benefits of market changes.
Apply for a Mortgage With Assurance Financial
When you’re ready to take the exciting step of purchasing a new home, work with Assurance Financial to take advantage of historically low rates.
We make it easy to apply for a mortgage and estimate costs during the process, and you can get pre-qualified in 15 minutes. Our licensed, approachable, trustworthy loan officers have the industry knowledge and expertise to get you custom competitive rates. And we have just about every type of home loan available, from conventional loans to FHA and VA loans to loans designed specifically for jumbo or modular homes.
Whether you’re a first-time homeowner, downsizing, dreamsizing or looking for an investment property or a vacation home, we can make getting started with your loan quick and convenient. And because we’re an independent lender rather than a mortgage broker, we give you the security and peace of mind of knowing we’ll never pass your loan or personal data on to anyone else.
Apply online, or contact us today for a no-obligation quote.
Sources:
- https://files.consumerfinance.gov/f/documents/cfpb_market-snapshot-first-time-homebuyers_report.pdf(4)
- https://assurancemortgage.com/everything-you-need-to-know-about-30-year-fixed-rate-mortgages/
- https://assurancemortgage.com/how-to-get-a-mortgage-loan/
- https://assurancemortgage.com/does-pre-approval-affect-credit-score/
- https://assurancemortgage.com/loan-application-process/
- https://assurancemortgage.com/what-is-down-payment-home-loan/
- https://assurancemortgage.com/what-are-closing-costs/
- https://assurancemortgage.com/what-is-a-mortgage-payment/
- https://fred.stlouisfed.org/graph/?g=NUh
- https://www.forbes.com/advisor/mortgages/mortgage-rates/
- https://www.forbes.com/advisor/mortgages/mortgage-interest-rates-forecast/
- https://www.consumerfinance.gov/ask-cfpb/when-can-i-remove-private-mortgage-insurance-pmi-from-my-loan-en-202/
- https://assurancemortgage.com/calculators/
- https://assurancemortgage.com/how-do-you-calculate-your-estimated-mortgage-payment/
- https://www.investopedia.com/ask/answers/081516/how-many-mortgage-payments-can-i-miss-foreclosure.asp
- https://assurancemortgage.com/refinance-your-home/
- https://assurancemortgage.com/purchase-your-home/
- https://assurancemortgage.com/apply/
- https://assurancemortgage.com/contact-us/
After months of searching, you’ve finally found the perfect house. Congratulations on your exciting milestone! While you’re undoubtedly excited about this opportunity, it’s a good idea to be careful during this time to avoid jeopardizing your application approval.
Some of the top things to avoid after applying for a mortgage include:
1. Don’t Deposit Large Sums of Cash Into Your Bank Account
Lenders need to source your money, and cash is often difficult to trace. Before making any large deposits, it’s wise to ask your loan officer how to properly document that money.
2. Don’t Change Your Bank Account
It’s essential to remember that lenders will always need to source and track your assets. A consistent bank account makes it easier for lenders to identify and track your funds. Talk to your loan officer before transferring any money to a new account.
3. Don’t Make Any Large Purchases
Making purchases such as furniture or a new car adds to your monthly debt and increases your debt-to-income ratio. For a lender, this higher debt ratio places you at a greater risk of being unable to repay your mortgage. In some cases, qualified buyers with new debt may no longer qualify for a home loan.
4. Don’t Change Jobs or How You Receive Payments
Your loan office will track how much you earn each week and your income source. If possible, avoid switching to self-employment or changing to a commission-based income during this time.
5. Don’t Co-Sign on Another Person’s Loan
When you act as a co-signer on a loan, you take on responsibility for ensuring the payments are made. Even if you are not paying on the loan yourself, the lender will still consider it to be new debt.
6. Don’t Start Applying for New Credit
Whether you’re applying for a new credit card or a vehicle loan, when you have your credit history checked by organizations across multiple channels, it will impact your credit score. Your credit score is a key determiner of the interest rate on your mortgage and may affect your loan eligibility.
7. Don’t Close Your Credit Accounts
Borrowers often mistakenly believe that limiting available credit will improve their chances of approval. However, a significant element of your credit report is the depth and length of your credit history. As such, closing accounts can negatively impact your score.
8. Don’t Miss Your Payments
Missing a bill or paying late will impact your credit score. Even one late payment can decrease your credit score to the point where you will no longer be eligible for your new mortgage. If you want to ensure you qualify for your mortgage, make sure you pay all of your bills on time.
Secure a Mortgage With Assurance Financial
At Assurance Financial, we want to help you secure a mortgage and achieve your dream of owning a home. Our team is here to simplify the process and educate you on what to avoid when getting a mortgage to prevent jeopardizing your application. We offer several mortgage options to meet your needs, including conventional, FHA, jumbo and VA loans.
When you choose our expert financial services, we will help you find a personalized mortgage payment plan. Contact a team member today to learn more about how we can help you secure a mortgage so you can buy your dream home!
There are many factors to consider when selling a home, and you may be wondering what happens to your mortgage when you move. After all, the 2018 American Community Survey found that the median length of time homeowners stayed in their homes was 13 years, a shorter length of time than most mortgage terms.
Recent data from the Pew Research Center found that at the end of the fourth quarter of 2020, the rate of American households that owned their own home increased to around 65.8%. With so much homeownership throughout the country, mortgages are an imperative topic. If you’re one of the many Americans that own a home with a mortgage, you should know your options when it comes time to sell.
Here’s a comprehensive guide to what happens if you sell your house and still owe money.
Topics Covered
- Should I Pay Off My Mortgage Before Selling My House?
- What Happens to My Mortgage When I Sell My House?
- Selling Your Current Home Before Buying Another
- Buying a New Home Before Selling Your Current One
- How to Get a Mortgage on a New Home
Should I Pay Off My Mortgage Before Selling My House?
If you plan to move and already have a mortgage on your current home, your first thought may be to pay off your mortgage early, so you’re free of your monthly payments. Though it isn’t necessary to pay off a mortgage before you sell your house, it may be a viable option depending on your situation. This option requires some planning, but you can make it happen.
There are several benefits to paying off a mortgage early:
- Saves interest fees: Over the life of a 15- or 30-year loan, interest can stack up and sometimes double what homeowners pay, despite their original loan amount. When homeowners decide to pay their loan off early, they get to eliminate some of the interest they would pay in the future and save themselves years of payments.
- Frees up monthly funds: This process also opens up more funds in your monthly budget, giving you greater flexibility with that cash later in life. When your mortgage payments are gone, you could contribute that money into your emergency fund, retirement account or other investments, or save up for that vacation you always planned.
Many variables can factor into your decision, so it’s essential to crunch the numbers and examine your financial situation individually.
Here are two of the most common strategies to pay off your mortgage early:
1. Higher or More Frequent Payments
One of the simplest ways to decrease the life of your mortgage is to make payments more often. Although bi-monthly payments will cost the same amount as your previous mortgage payments, they’ll use the weeks of the year to give you an additional annual payment. When multiplied over several years, one extra yearly deposit can lead to a considerable amount of savings.
Consider increasing your monthly payments, consistently paying more on your mortgage than the minimum requirement. Manually adding extra is a flexible option that allows you to contribute any amount you choose. Add $100 more, $50 more or any variable amount you decide to contribute over your loan’s life.
2. Refinancing
Some homeowners choose to fix their loan for 30 or 40 years but may later decide to pay it off sooner. By refinancing your mortgage, you can refigure your loan for a shorter timeframe, increasing your monthly payments and decreasing your interest.
However, refinancing may not be the best idea when you’re looking to move. Some homeowners may want to refinance to put the money they would have spent on interest payments toward their savings for a down payment. If your savings don’t add up before your planned move, a refinance could cost you more money than it’s worth. Use Assurance Financial’s refinance calculator to determine whether a refinance is right for you.
Ultimately, choosing to pay off a mortgage before you move may not be your best option. Depending on your timeframe and your other investment opportunities, you may decide to keep that cash and set it aside for a new down payment. Whatever you choose, weigh your choices and consider which is in your best interest.
What Happens to My Mortgage When I Sell My House?
According to Freddie Mac, almost 90% of American homeowners finance their homes with a 30-year mortgage. Still, many homeowners will move to another house before that timeframe ends. This situation is common, so you can follow standard practices for selling a home with a mortgage attached.
If you’re selling your house before the mortgage term is up, you can take one of two avenues:
1. Traditional Home Sale
In a traditional home sale, the seller lists the house for a price that will cover the following costs:
- The mortgage’s remaining costs
- Existing home equity loans or home equity lines of credit (HELOCs), if applicable
- Mortgage prepayment penalties, if applicable
- Closing costs, including agent commissions, taxes and other fees
After taking care of the above expenses, whatever amount is left over is the seller’s profit. To pay for the rest of the mortgage, the closing manager sets up an escrow account into which the buyer will deposit their payment. Then, the title company will distribute the final mortgage payment to the lender. As a result, the seller no longer has that mortgage.
If you’re unable to sell your home for enough money to cover the associated costs, you’ll have to pay them out of pocket, wait until you can sell the house for more or request a short sale. In an ideal situation, the seller can cover the remaining balance of their loan, pay for closing costs and put a down payment on their next home from the sale price. This scenario requires good home equity — which is the homeowner’s financial stake in their house — to warrant a high enough price.
A home’s equity is comprised of the following elements:
- The original down payment
- The home’s gains in market value
- Mortgage principal payments
- The cost of renovations or improvements the seller made to the house
Getting a quote for your mortgage payoff when selling your house helps determine the price you need to sell your home. A mortgage payoff shows you the total amount you need to pay to settle your mortgage debt, including your interest and other unpaid fees. If you tell your lender about your plan to sell your home, they’ll provide you with a mortgage payoff quote.
2. Short Sale
When your house has too little equity to pay for your mortgage, it has negative equity. Without enough cash to cover your remaining mortgage balance, plus the closing costs, a short sale may be your only option. In a short sale, the buyer purchases the home for less than the seller’s debt against the property. These sales require approval from your lender because they leave the mortgage company at a financial loss.
The approval process for a short sale usually takes longer than for a traditional sale since the seller has to convince the lender they can’t pay off their loan. To convince the lender, the seller must either show that the housing market dropped, so their home is worth less than their debt, or prove they’re incapable of keeping up with their payments. Because the lender is trying to recoup as much of their losses as they can, the process may take a while.
Another negative aspect of short sales is they remove the seller’s negotiating power. This entire process depends on the lender’s approval, including the sale of the house. Even when the buyer and seller agree on a price, the lender may end up declining the buyer’s offer to hold out for a higher one. Ultimately, short sales negatively affect a seller’s credit score and make it more challenging to get a home in the future.
Selling Your Current Home Before Buying Another
If you’ve examined all of your options and want to go ahead with the sale of your home, you may want to know whether you should sell it before or after buying a new one. This answer could be as simple as establishing how much you have in savings to spend on a down payment. Most sellers find that selling their current home opens up their home’s equity so they can use that profit for their next home.
Pros of Selling First
By selling first, you can enjoy the following benefits:
- More negotiating power: When you buy a new house before selling your current one, you put more pressure on yourself to sell quickly and at a high price. Depending on what strategy you use to purchase a new home while still responsible for an old one, you may feel compelled to accept the first offer you receive. However, selling first allows you to negotiate with buyers and wait to sell until you get the offer you want.
- Less pressure: Buying a new home before someone purchases your old one puts you on a crunched timeline to get rid of your current home as fast as possible. Waiting for the right buyer while paying for two properties can be a lot to handle. If you sell first, you can take your time considering sales strategies and making any renovations or repairs.
- Total equity for future purchases: Perhaps one of the most compelling reasons to sell before buying another house is the potential to tap into your current home’s equity when you make your next purchase. If you pocket a considerable profit, you may be able to pay a larger down payment and take out a smaller mortgage on your next home. With a high enough profit, you may even be able to offer cash, which is very appealing to sellers.
For the above reasons, selling a current home before buying another is usually the most straightforward course to take. When stepping into the market to purchase a new home, the lack of pressure on your time and funds can help you make the best decision regarding a sale and give you more money to put toward your next home.
If you’re in a seller’s market, selling before buying can be even more profitable. In a seller’s market, sellers have the upper hand in negotiations because there are fewer homes than potential buyers. This situation gives sellers the ability to keep their asking price high or even raise it. Because there’s such high demand, homes usually sell quickly in a seller’s market.
Cons of Selling First
However, selling before buying could also cause some logistical concerns. If you sell your home quickly, you might have to find temporary housing before purchasing your new home. When there’s a lot of competition in the housing market, a seller could reject your offer, and the property could go to another buyer. Should that happen unexpectedly, you might need to move your belongings into a rental unit or pay for storage until you can move somewhere else.
Before deciding when to sell, calculate the costs involved and whether you may experience a time crunch when going to buy. There may be a situation where timing forces you to move in with a friend or sublet an apartment for a while. That said, the cost of moving twice and storing your furniture and belongings until you buy a new house generally won’t outweigh the benefits of selling before buying a new home.
[download_section]
Buying a New Home Before Selling Your Current One
Sometimes, buying first can be appealing when you can afford to buy without recovering the equity in your old home or you’re in a buyer’s market and have negotiated an excellent deal for a house. This option may require some extra steps and additional help with financing the purchase. If you’re unable to pay for a new home out of pocket, you have several options for financing:
1. Home Sale Contingency
A home sale contingency is a clause you can include in your offer to purchase a house. This clause tells the seller you need to find a buyer for your own home before closing on the purchase. A sale and settlement contingency gives you the legal right to exit a contract if you don’t receive an offer for your current home in time. A settlement contingency protects you if an offer on your old home falls through.
A significant drawback to a home sale contingency is that it could make your offer less competitive to sellers. If the seller sees you can’t make a firm offer, they could pass over you in favor of a committed buyer when negotiating a deal. If you’re only able to make less competitive offers, buying a home could take longer. However, if the seller accepts your offer, you’ll be able to keep the home you want under contract while you wait for a buyer.
2. Bridge Loan
Another option for financing a purchase is taking out a bridge loan. These are short-term loans designed to bridge the time between when a homebuyer needs financing and when it becomes available. With a bridge loan, you can access the resources you need to pay for your current mortgage and make a down payment toward your new house.
These loans can be a simple way to get financing quickly. Note that you’ll need to make monthly payments on the bridge loan while also paying for your existing mortgage. However, when you sell the old home, you can use your profit to pay off the bridge loan. If your home takes a while to sell, you could be paying two mortgages on top of the bridge loan payments as you wait.
3. Two Mortgages
If you can afford it, carrying two mortgages may be the least complicated option for financing a home. Maintaining two mortgages while you wait for your old house to sell can keep you from entering into another loan like a bridge loan.
However, carrying two mortgages at once probably doesn’t sound enjoyable. The cost of two mortgages can become steep, so you may not be interested. Still, it could give you greater freedom to make an offer without being tied to a home sale contingency.
How to Get a Mortgage on a New Home
Whether you’ve already sold your old home or are just beginning the house-hunting process, you’ll need a mortgage before closing on a new house. Here are the steps you need to take to be ready to make that purchase and move into your next home.
1. Save for a Down Payment
The down payment may look different depending on whether you’ve already sold your old home. With the profits from your old home in your pocket, you can use it for a down payment along with any other funds you saved. Because a larger down payment means a smaller loan size, choosing to save the money you would have spent on your morning later can go a long way.
If you’re buying a home without the benefit of your previous home’s equity, you may qualify for a conventional loan with a down payment of only 3-10%. There are also mortgage programs that require as little as 0% down, like United States Department of Agriculture (USDA) loans and Veterans Affairs (VA) mortgages. With certain qualifications, you can reduce the amount you need for a down payment and avoid paying for private mortgage insurance.
2. Explore Mortgage Options
Before applying for a loan, consider which loan types are most beneficial for you in your financial situation. Some homebuyers choose to go with a conventional mortgage with 15-, 20- or 30-year loan terms. Special considerations — such as your credit score, veteran status or location — can qualify you for other loan types. With some careful research and the help of our dependable loan advisors, you can find the best mortgage type for your needs.
Also, think about what features you want in a house and what you’re willing to sacrifice. It may be best to buy a smaller or less updated home to keep your mortgage debt lower or concentrate your monthly debt payment on loans with higher interest rates, such as school or credit card payments. On the other hand, you may be comfortable buying at the higher end of your price range if you have few or no other debts.
3. Complete an Application
Once you’re ready, you’ll want to apply for the mortgage of your choice. To apply, you’ll need some paperwork, including:
- Your last two years of completed personal tax returns
- Your business’ previous two years of tax returns, if applicable
- Proof of income from a 30-day period, like pay stubs and bank statements
- Photo identification like a driver’s license
- Your last two years of W2 forms
Once you have your forms in order, you can apply online, and your lender will look over your financial information to give you an estimated interest rate. With the online application at Assurance Financial, you can submit all of this documentation in as little as 15 minutes and get pre-qualified for a loan within 24 hours.
4. Wait for Processing and Underwriting
Once you’ve found the home you want and the seller has accepted your offer, your lender sends your financial information over to a loan processor, who double-checks all of the details and will contact you if they need any clarification.
After processing, your lender will likely order a home appraisal to determine the value of the property you intend to buy. Once an appraiser looks over your home, a loan underwriter will review your credit score and application once more to make the final approval. This stage finalizes the amount of your loan and your interest rate.
5. Head to Closing
When your loan is cleared, you can begin the final steps in your journey to homeownership. The title company will set up a closing day with you, and you can sign many of your closing documents online beforehand.
On closing day, you’ll bring your down payment in the form of a cashier’s check, plus any other fees and closing costs you may be required to pay. Alternatively, you can choose to set up a wire transfer for the funds. After you sign the last bit of paperwork, you’ll get the keys to your new home.
Get Started With Assurance Financial
If you’re looking to get a mortgage for your new home or refinance an old mortgage, Assurance Financial is ready to help. We provide complete support at every step of your loan application, and our licensed loan officers are experts at getting the home loan that best suits your needs. With a variety of loan types and competitive rates, we provide mortgage solutions for homebuyers at any stage of life.
At Assurance Financial, we understand you want a smooth mortgage process that leads you to your dream home. To get started and discuss your mortgage options, find a loan officer today and see why Assurance Financial stands out from other online mortgage lenders.
Linked Sources:
- https://assurancemortgage.com/paying-off-mortgage-early/
- https://assurancemortgage.com/calculators/should-i-refinance-my-mortgage/
- https://myhome.freddiemac.com/blog/homeownership/20190815-mortgage-options
- https://www.consumerfinance.gov/ask-cfpb/what-is-a-payoff-amount-is-my-payoff-amount-the-same-as-my-current-balance-en-205/
- https://assurancemortgage.com/everything-you-need-to-know-about-usda-rural-loans/
- https://assurancemortgage.com/5-things-know-va-loans/
- https://assurancemortgage.com/what-is-a-conventional-mortgage/
- https://assurancemortgage.com/apply/
- https://data.census.gov/cedsci/table?q=duration%20of%20homeownership%202018&tid=ACSDP1Y2018.DP04
- https://www.pewresearch.org/fact-tank/2021/03/08/amid-a-pandemic-and-a-recession-americans-go-on-a-near-record-homebuying-spree/